
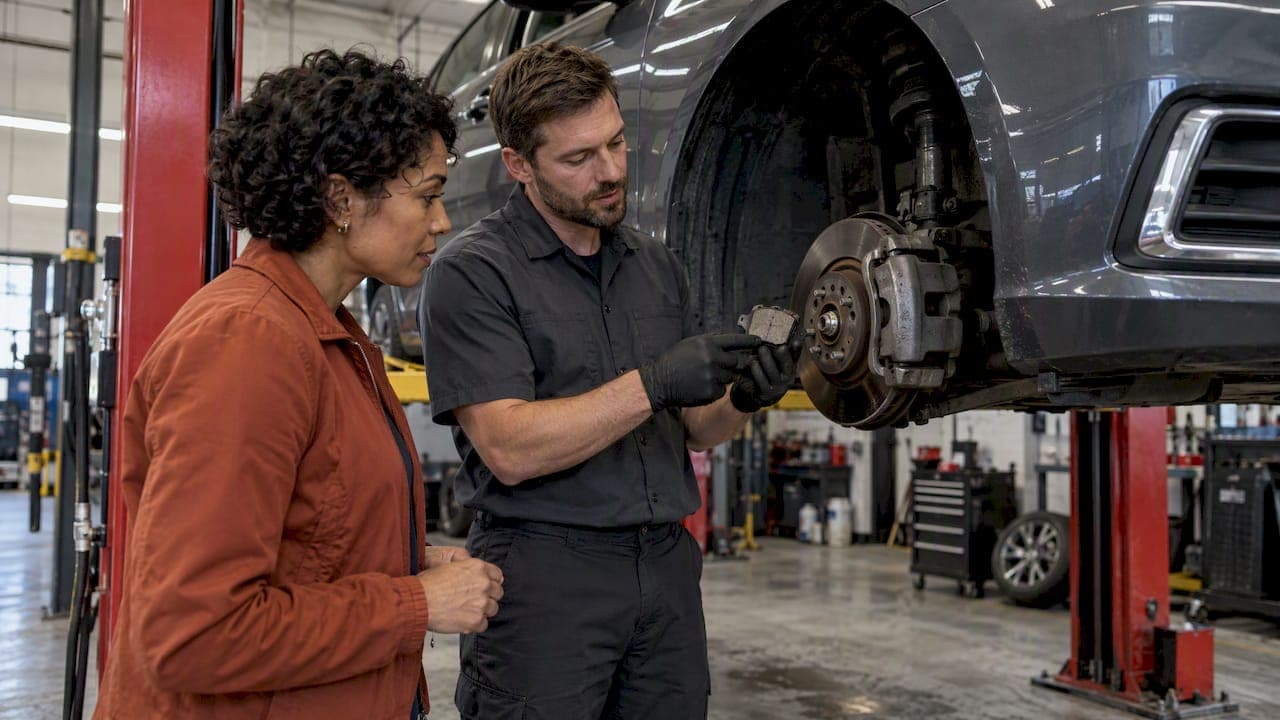
A warranty rarely means $0 at the shop. With an extended car warranty, your out-of-pocket cost usually comes from four places: the deductible, work the contract does not cover, charges above what the administrator will authorize, and anything you ask the shop to add. Know those four and you can read any contract and estimate your real cost before a repair ever happens.
This guide walks through each one. It also shows how the math plays out on higher-end vehicles such as Range Rover, BMW, Mercedes-Benz, Porsche, Ford and Honda, where one repair can cost more than many drivers expect.
TL;DR
- Most extended coverage is a service contract, not a warranty in the federal legal sense, so the contract's wording decides what you pay, not the label on the brochure.
- Expect to owe your deductible, per visit or per repair depending on the contract, plus anything outside covered components.
- Diagnostics, taxes, fluids, shop supplies and labor or parts above the authorized amount can still land on your bill.
- Maintenance records, pre-approval rules and shop restrictions are the most common reasons a claim leaves you paying everything.
- Luxury and performance vehicles raise both the odds and the size of an out-of-pocket bill, so coverage level matters more than the monthly price.
Table of Contents
- What "out of pocket" means with a warranty
- The four ways you end up paying
- Claim rules that can turn a covered repair into your bill
- When the repair costs more than the car is worth
- What it looks like on the cars people actually drive
- A simple way to estimate your out-of-pocket cost
- Is it worth it? The honest case on both sides
- Perspective: what we tell owners who ask about out-of-pocket costs
- Getting a quote that shows your real cost
- Pressure at the dealership
- FAQ
- Sources
What "out of pocket" means with a warranty
Out of pocket is whatever you pay from your own money on a repair, after the contract has done its part. With an extended plan, that is almost never zero.
The Federal Trade Commission points out that an extended warranty is technically an auto service contract, an optional add-on product and not a warranty as federal law defines the term. That sounds like a technicality, but it has a practical effect. A manufacturer's factory warranty comes with the car. A service contract is an agreement you buy, and it pays for what its terms say it pays for, under the conditions it sets.
The same FTC page notes that you may owe a deductible for each service visit or for each individual repair, depending on the contract, and that you pay for any work falling outside the coverage. So the first question to ask of any contract is not "what does it cover?" but "how do I get from a failed part to a paid claim, and what is left for me at each step?"
The four ways you end up paying
1. The deductible
The deductible is the amount you agree to pay on a covered repair before the contract pays the rest. It is the most visible out-of-pocket cost, and it is the one you can plan for.
Two details change the total more than the dollar figure does:
- Per visit or per repair. Under a per-visit deductible, a shop that fixes three covered items in one trip charges you once. Under a per-repair deductible, each covered item can carry its own deductible. The FTC says the contract terms decide which applies, so find that sentence in your agreement.
- Deductible tiers. Some contracts set different deductibles by component or by where the repair is done. Read the schedule, not just the headline number.
A "disappearing deductible" is a feature some contracts advertise in which the deductible is waived if you return to a specific repair facility, such as the selling dealer. Terms vary a great deal, and the waiver often depends on where you take the car. If a plan offers one, ask for the exact conditions in writing, including whether it applies to every visit or only to certain shops.
2. Work the contract does not cover
Coverage lists decide this. According to the FTC, service contracts typically do not cover accident damage or normal wear and tear. A covered component is paid for. A failed part that is not listed is entirely yours.
This is why the tier you choose matters. A plan that lists named components covers only what it names. A plan that covers everything except a list of exclusions generally leaves you exposed to less. Our own range is built around that idea: Elite, Advanced and Essential cover progressively more of the vehicle, so you can match the plan to the car and the budget.
3. Charges above what the administrator authorizes
A covered repair is not always paid in full. You may owe money when a shop's labor rate or parts price is higher than the amount the administrator authorized. This is common at high-end dealerships and specialty shops, where hourly labor rates run well above those of an independent garage.
Here is an illustration with made-up numbers. Suppose a shop quotes 10 hours of labor at $210 an hour, which is $2,100. The contract authorizes labor at $160 an hour, which is $1,600. You owe the $500 difference, plus your deductible. Nothing was denied, and you still paid.
4. Extras and fees around the repair
A claims-help resource lists the usual suspects: diagnostic charges, taxes, fluids, shop supplies, and labor or parts above the authorized amount. It adds that you may also owe for customer-requested work done during the same visit. If you approve a brake job while the car is already on the lift for a covered repair, the brake job is your cost.
Before you sign, ask how diagnostics are handled. Some contracts pay for teardown only when the failure turns out to be covered. Others treat diagnostic time differently. That one answer can change your bill by hundreds of dollars.
Claim rules that can turn a covered repair into your bill
The worst out-of-pocket outcome is a denied claim. The FTC lists the ordinary causes:
- Where you can repair. Contracts may restrict which shops can do the work.
- Pre-approval. Some require authorization before the shop starts. A repair done first and submitted later may not be paid.
- Maintenance. Skipping manufacturer-recommended maintenance might void the contract, and claims may be denied if you cannot produce records.
The habit that protects you is simple. Keep every oil change, fluid service and inspection receipt in one folder, digital or paper. Photograph each one. On a European luxury car with short service intervals, that file is your most valuable document if a claim is questioned.
Also check the dates. The FTC warns that a service contract may duplicate coverage you already have from the manufacturer, so compare the coverage and the dates before buying. If the factory warranty still has time left, you may be paying for overlap.
When the repair costs more than the car is worth
A question that comes up often: what if the engine fails and the repair costs more than the car's market value? Say the car is worth $14,000 and the repair is $18,000.
The answer is in the contract. The FTC notes that some contracts apply a depreciation factor, paying only part of the repair or replacement cost based on the vehicle's mileage. Others set a per-claim limit or a total limit over the life of the agreement. Look for three things:
- The per-claim cap, if any.
- The aggregate cap across all claims.
- Whether the payout is tied to the car's value or mileage.
A contract with no per-claim cap and no depreciation factor behaves very differently from one with both, even if the monthly price looks the same.
What it looks like on the cars people actually drive
The stakes depend heavily on the vehicle. Below are common ownership pain points for popular higher-end makes and what they mean for out-of-pocket risk. These are general patterns owners and independent shops discuss, not a promise about any particular car. Individual vehicles vary by year, mileage and maintenance history.
Range Rover and Land Rover
Range Rover models are known for their air suspension, which gives the ride its signature cushion and adjustable height. It is also a system with many parts that can wear: air springs, compressors, height sensors and valve blocks. Electrical and infotainment modules are another area owners often mention, since the cabin is packed with technology.
The out-of-pocket risk is the labor rate and the parts price. A contract that names suspension and electrical components, and pays a realistic labor rate, matters far more here than a low deductible.
BMW
BMW owners enjoy sharp handling and strong engines, and the brand's cooling systems, gaskets and oil-leak points are commonly discussed topics at independent shops. Plastic cooling components such as water pumps, thermostats and expansion tanks are often cited as wear items on some generations. Turbocharged engines add components that run hot.
Cooling and engine coverage is the priority. Ask whether the plan treats seals and gaskets as covered, because on many contracts they are covered only when a covered part is being replaced.
Mercedes-Benz
Mercedes-Benz vehicles pack in driver-assistance sensors, adaptive suspension, large touchscreens and complex electrical architecture. When one module fails, the diagnostic time can be significant, and the module itself can be expensive.
For these cars, check the electronics and high-tech coverage, and ask how diagnostics are paid. Our plans address high-tech electronics, electrical systems and steering and suspension, which are the areas that tend to drive the largest bills on cars like this.
Porsche
Porsche owners buy for performance, and performance parts work hard. Coolant lines, ignition components, clutches and transmissions on sporty variants all see heavy use. Even a well-kept Porsche is serviced at specialist rates, so labor above the authorized amount is a real risk.
If you drive a 911, Cayman, Macan or Cayenne, ask how the contract treats performance-use wear and whether track or competitive driving is excluded. Many contracts exclude it, and that exclusion is an out-of-pocket trap.
Ford
Ford's range is wide, from trucks to SUVs to the Mustang. Owners of EcoBoost turbocharged engines and ten-speed automatic transmissions often discuss those systems when they think about coverage, and modern F-150s and Explorers carry a lot of sync and sensor electronics. Because Ford parts and labor are generally more affordable than European luxury, a middle tier may be enough for a daily driver. A truck used for towing or work is a different story: check how the contract defines commercial or heavy use.
Honda
Honda has a strong reputation for reliability, and that is exactly why owners sometimes skip coverage. The risk is lower, but not zero. Owners of some Civic, Accord, CR-V and Pilot model years discuss air conditioning components, infotainment screens, and continuously variable or multi-speed transmissions. For a Honda with 80,000 or more miles, a basic plan covering engine, transmission and cooling may protect against the one big repair that would otherwise hurt.
Other makes
We also publish make-specific pages, including coverage guides for Volkswagen and Lotus, with a dedicated page for the Lotus Elise. For two wheels, there is a Ducati page, and our Full Throttle motorcycle plan covers riders.
A simple way to estimate your out-of-pocket cost
Before you buy anything, run this check on the contract in front of you.
- Write the deductible and its type. Per visit or per repair? Any tiers?
- List the likely failures for your car. Use the make-by-make notes above as a starting point, then ask your independent mechanic what they see most.
- Check each against the coverage list. Named component, or exclusions-only?
- Find the labor rate. Compare the authorized hourly rate to what your preferred shop charges.
- Check the caps. Per claim, total, and any depreciation factor.
- Read the claim steps. Pre-approval, shop restrictions, maintenance records.
Here is the worked example, again with illustrative numbers. A covered cooling system repair on a luxury sedan comes to $2,400 for parts and labor. The contract's deductible is $100, shop supplies are $45, and tax is $70. Labor is $180 above the authorized rate. Your out-of-pocket cost is $100 + $45 + $70 + $180 = $395, and the contract pays the remaining $2,005. Without the contract, the whole $2,400 would have been yours.
The number to compare is not the price of the plan. It is the plan price plus the expected out-of-pocket costs, set against what the repair would cost without coverage.

Is it worth it? The honest case on both sides
The Consumer Financial Protection Bureau suggests comparing the contract's cost and length, what it covers and excludes, how you plan to use the vehicle, and whether it overlaps with the manufacturer's warranty. It also mentions setting aside money each month for maintenance and repairs as an alternative.
Consumer Reports has long taken the cautious side. A 2008 release recommended putting the $1,500 to $2,300 you would spend on an extended warranty into a savings account or fund instead, and its buying guide still suggests a dedicated repair fund. Those figures are from 2008, so treat them as a way of thinking, not as today's prices.
The savings approach works when you can absorb a surprise bill without strain. It works less well on a vehicle where one repair, such as an air suspension rebuild, a transmission or an engine, can run into thousands of dollars before your fund has built up. The more a car costs to fix, the more a contract's cap on your worst-case bill is worth. The right choice depends on your cash cushion, how long you will keep the car and how much a single big repair would disrupt you.

Perspective: what we tell owners who ask about out-of-pocket costs
We talk with owners every week who assumed "covered" meant "free." It rarely does, and we think the honest approach is to say so up front. A good contract does not remove every cost. It removes the catastrophic ones and makes the rest predictable.
That is why we built our process around four steps: a consultation, plan selection, customization and a final agreement. The consultation is where we ask about your vehicle's year, make, model and mileage and how you drive it. Customization is where you decide how much of the risk you want to carry yourself, usually by choosing between Elite, Advanced and Essential coverage.
Our view is that a plan should be judged by the questions you can answer before you sign: what is the deductible, what is named, what is excluded and what happens when a claim is filed. We aim for clear terms and no hidden fees, and for claim approvals that move quickly, typically within 24 to 48 hours. Repairs are handled nationwide, including through ASE-certified mechanics.
If a plan cannot answer those questions in plain language, keep looking, whoever sells it.
— Kenneth
Getting a quote that shows your real cost
When you request a quote from us, bring the details that drive out-of-pocket cost: your vehicle's year, make, model, current mileage, how long you plan to keep it, and any repair history. Ask us to walk through the deductible, the covered components and the claim steps for the specific plan. We offer Elite, Advanced and Essential coverage for cars, plus roadside assistance and rental reimbursement, so you can see side by side how much of the risk each tier carries.
If you ride, the same process applies to our Full Throttle motorcycle plan. For common questions about how coverage works, our FAQ page is a good place to start, and you can begin a free quote from rpmwarranty.com.
Pressure at the dealership
One more out-of-pocket trap sits in the finance office. The CFPB says consumers generally cannot be required to buy an extended warranty to get an auto loan, and that you may look for a different dealer or lender if you feel pressured. You can buy coverage later, from a provider of your choosing, after you have compared terms.
If a contract is rolled into your loan and you pay the loan off early, you may be owed money back. The CFPB reports that borrowers are generally eligible for a prorated refund of prepaid premiums for the unused portion, and its examiners found servicers that failed to provide required refunds or credits for unused add-on products after early termination. Ask for it in writing when you pay off or sell the car.
FAQ
Do I always pay a deductible with an extended warranty?
Not always, but most contracts have one. Some plans advertise a $0 deductible, and others reduce it under certain conditions. A lower deductible often comes with a higher plan price, so compare the total, not only the deductible.
What can I owe even when a repair is covered?
You may owe the deductible, taxes, shop supplies, fluids and diagnostic charges, depending on the contract. You can also owe the difference when the shop's labor rate or parts price is higher than what the administrator authorized. Any extra work you request during the same visit is yours to pay.
What is a disappearing deductible?
It is a feature where the deductible is waived under conditions set by the contract, often when you have the repair done at a particular facility. The details vary, so get the exact terms in writing before relying on it.
What does a car warranty not cover?
Accident damage and normal wear and tear are typically excluded, according to the FTC. Claims can also be denied if you skip recommended maintenance and cannot show records, or if you ignore pre-approval and shop rules.
Are extended warranties worth it for luxury cars?
Often the case for coverage is stronger, because parts and labor cost more and electronics are complex. It still depends on the contract's coverage list, caps and labor rate, and on whether you could comfortably pay a large repair yourself.
Sources
- Auto Warranties and Auto Service Contracts, Federal Trade Commission
- Your Warranty Claim Was Covered, So Why Do You Still Owe Money
- What are the differences between a manufacturer's warranty and an extended vehicle warranty or service contract, CFPB
- Consumer Reports: Extended Auto Warranties Are a High-Priced Gamble, 2008
- Best Extended Warranty Buying Guide, Consumer Reports
- Am I required to purchase an extended warranty or GAP insurance to get an auto loan, CFPB
- CFPB Takes Action Against Wrongful Auto Repossessions and Loan Servicing Breakdowns